Risk review of the issuer Shigong Capital
A post on the “Go fund yourself!” channel helped a lot in preparing this material: t.me/gofundyourself/81. We recommend reading it!
Background
We received many private questions about Shigong Capital LLC, and even more were asked in various chats. For a long time we negotiated with the company by phone and e-mail to arrange a short interview, waiting weeks for each reply. In the end we persuaded the company to look at the questions we e-mailed. After that, the company stopped communicating with us.
High risks
Here are the risks that holders and potential buyers of Shigong Capital bonds may not have known about.
1. Shigong's manager has serious difficulties with one of its properties
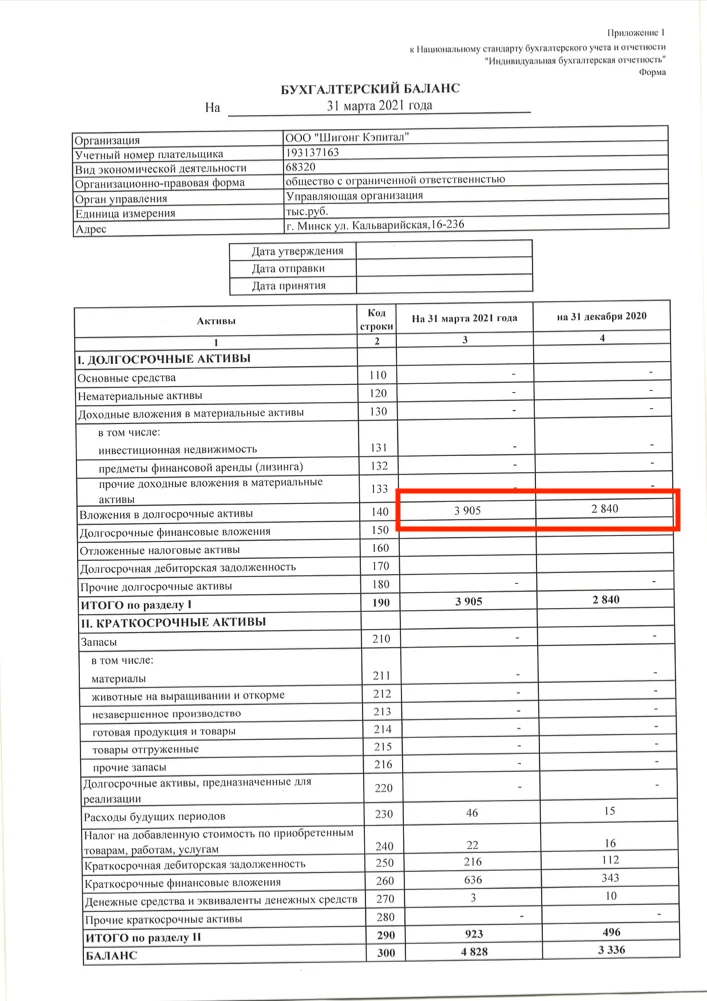
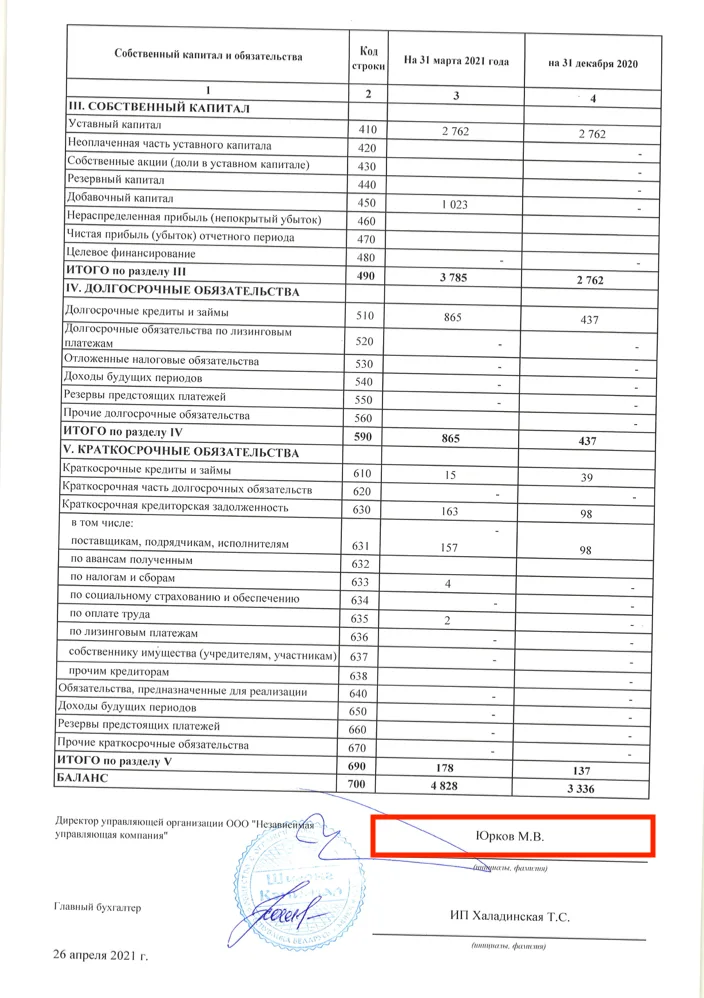
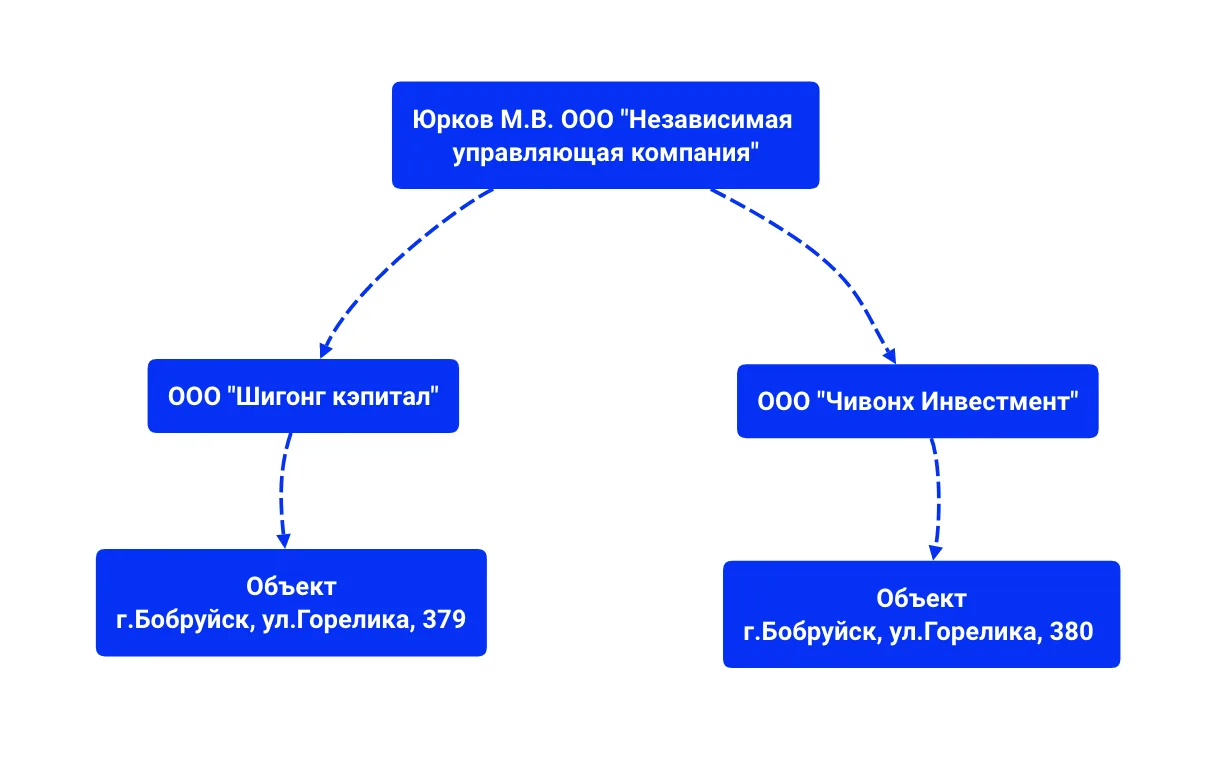
Some context. Shigong Capital LLC has on its balance sheet a building at 379 Gorelika St., Babruysk. It is an unfinished building pledged as collateral for the bonds, valued at 2.7 million as of 29 May 2020. As the balance sheet shows, this property makes up all of the company's net assets, and the company is managed by Independent Management Company LLC, represented by M. V. Yurkov:
This is what the property looks like on the map:
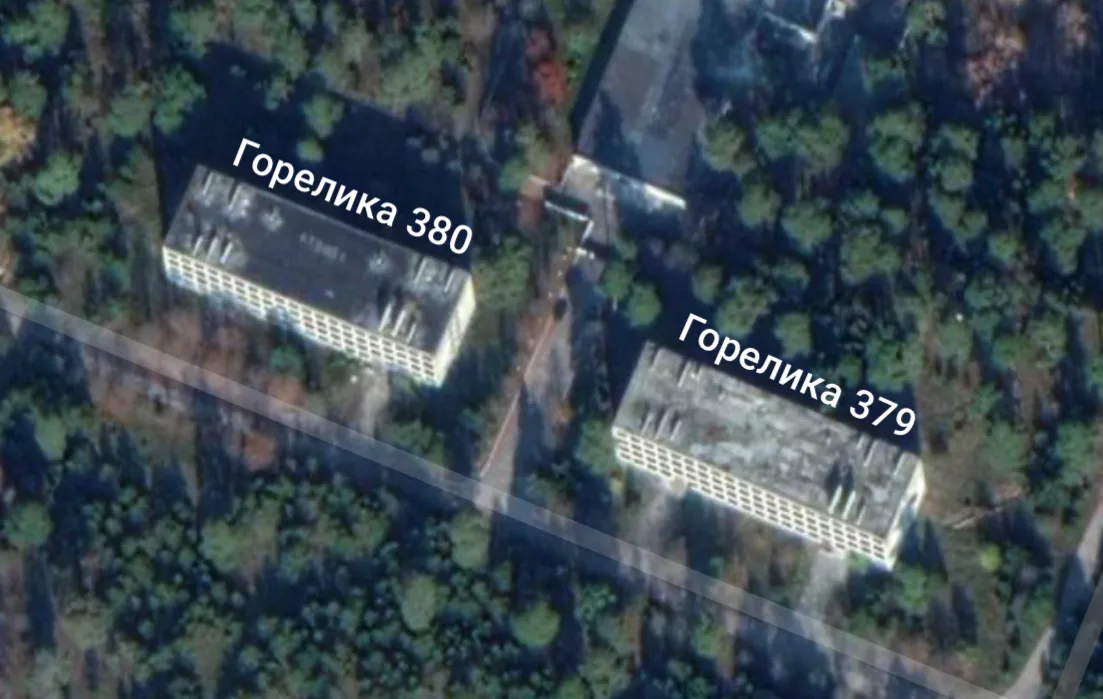
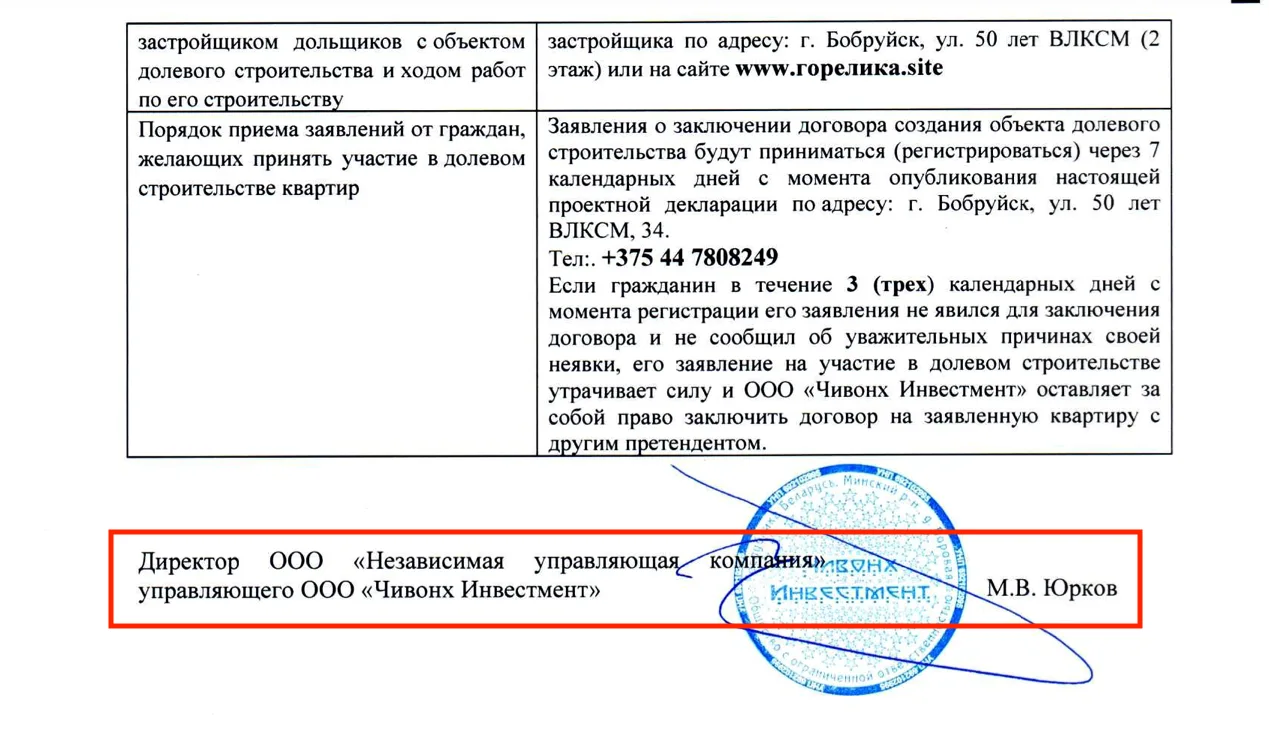
The property at 380 Gorelika St. (the neighbouring building) is developed by Chivonkh Investment LLC, which is also managed by Independent Management Company LLC, represented by M. V. Yurkov:
Schematically it looks like this:
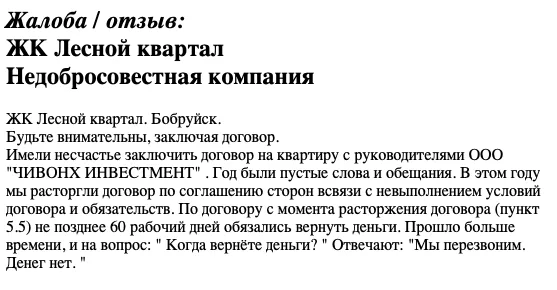
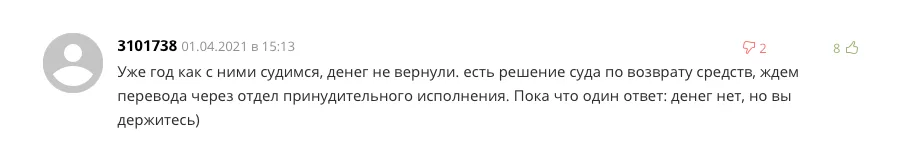
Chivonkh has serious trouble with the property at 380 Gorelika St. Here are just a few articles and reviews confirming that the company has serious problems completing the building and owes significant sums to buyers:
realt.onliner.by/2021/04/01/belorusy-odolzhili-zastrojshhiku-dengi
skargi.by/stroiteljstvo/7221-nedobrosovestnaya-kompaniya.html
2. The financial statements contain gross errors
Look at the latest income statement:
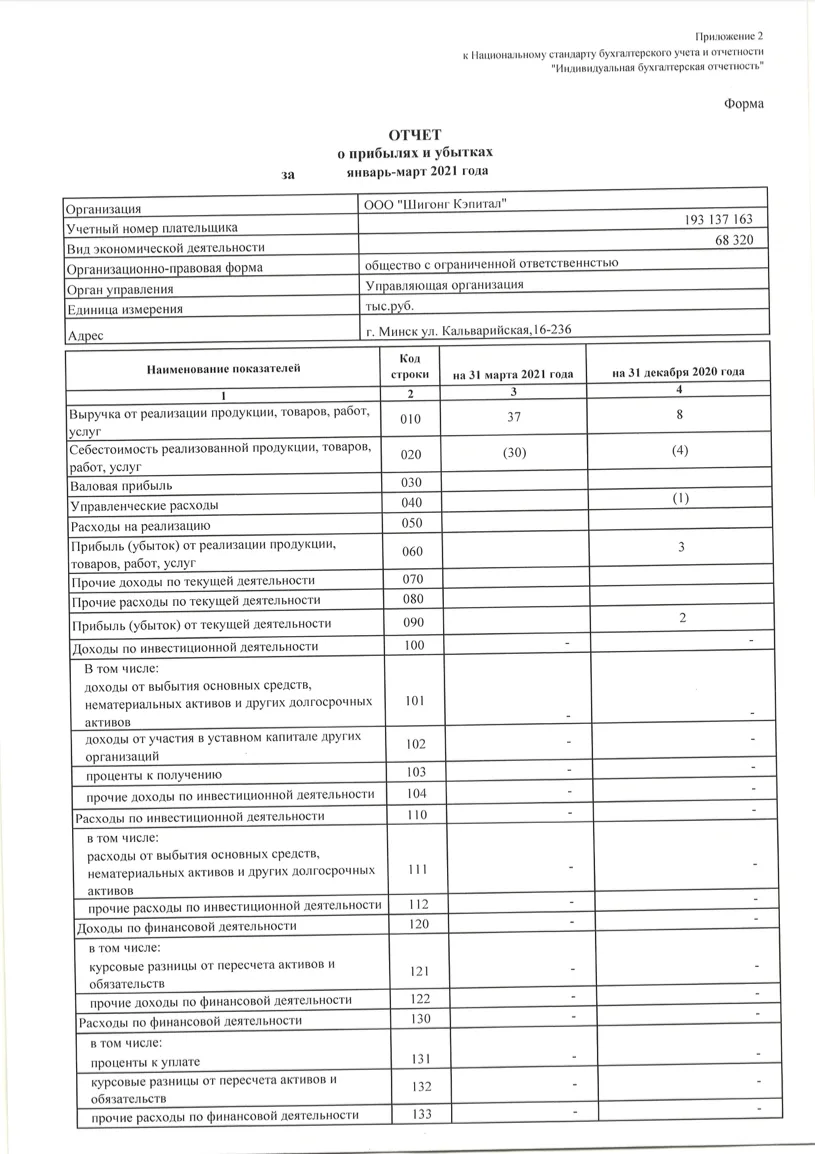
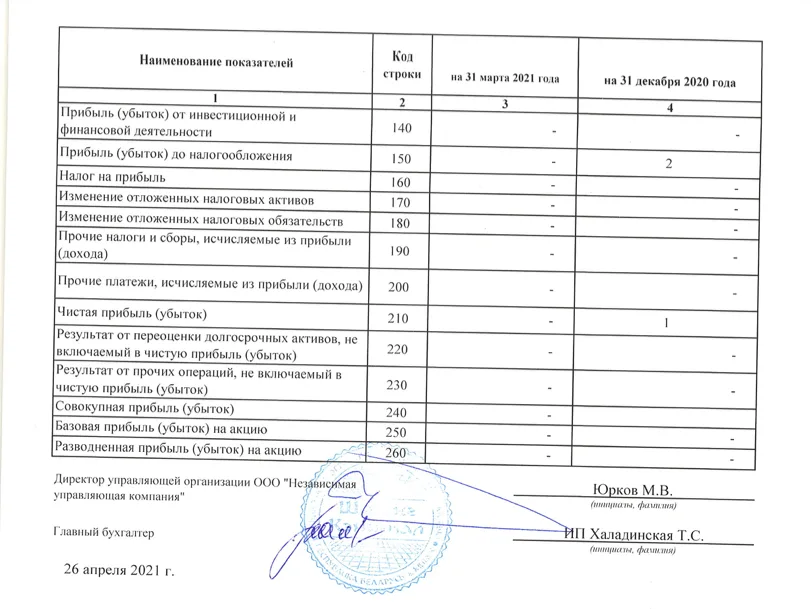
31 March 2021:
Revenue — BYN 37 thousand
Cost of sales — BYN (30) thousand
Profit — BYN 0 thousand
So according to Shigong's accountants, 37 − 30 = 0.
As you can see, the 2020 figures are no better.
In effect they understated net profit, which, based on these figures, means they underpaid tax.
3. The company does not generate enough profit to cover interest payments
The company issued USD 850 thousand of bonds. Yet in 2020 it earned just over USD 3 thousand in revenue and less than USD 500 in net profit. The coupon is 8.5% a year. To service even USD 100 thousand of bonds the company needs to generate at least USD 8.5 thousand of profit, and to service USD 850 thousand — just over USD 72 thousand a year. Currently the company earns nowhere near that. Its total debt is 190 times its operating profit.
4. The company's assets are illiquid
As described above, the company's main asset is an unfinished building in Babruysk valued at more than USD 1 million. We have some doubts that in the current situation it will be easy to sell an unfinished building without infrastructure on the outskirts of Babruysk.
Conclusion
The management company is embroiled in disputes with apartment buyers. Current profit is very unlikely to let the company service its growing obligations. The financial statements contain many errors. The company's assets will be extremely hard to sell. The company is highly opaque and refused to answer our questions.
What to do?
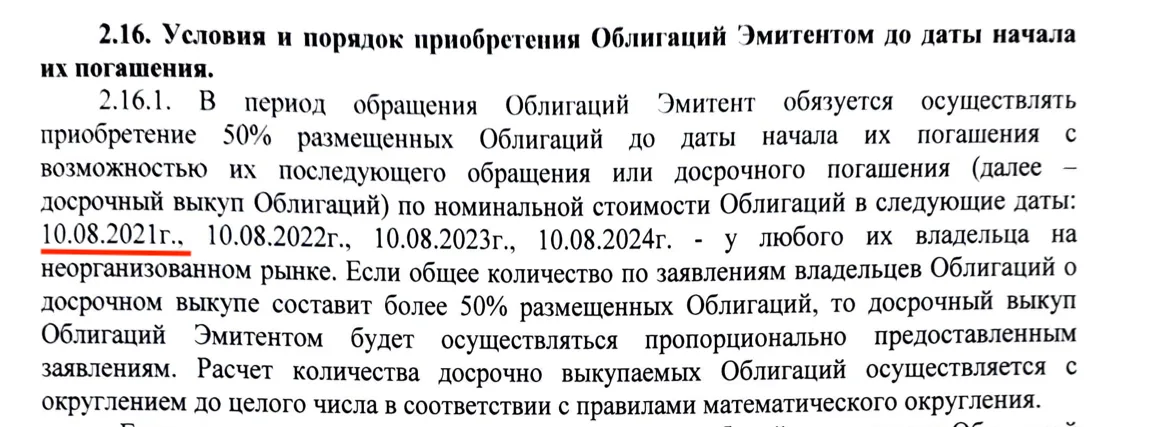
If you have not yet bought Shigong Capital LLC bonds, think twice about whether the yield is worth the risks. If you have already bought the bonds, you can require Shigong Capital to buy them back. You need to act fast: if you do not submit a put (early redemption) request within the next week, the issuer will not buy the bonds back, and the next opportunity will come only in a year. According to the prospectus, the issuer must buy back the bonds on request on 10 August 2021:
But you must submit the put request no later than 30 business days before the buyback date:
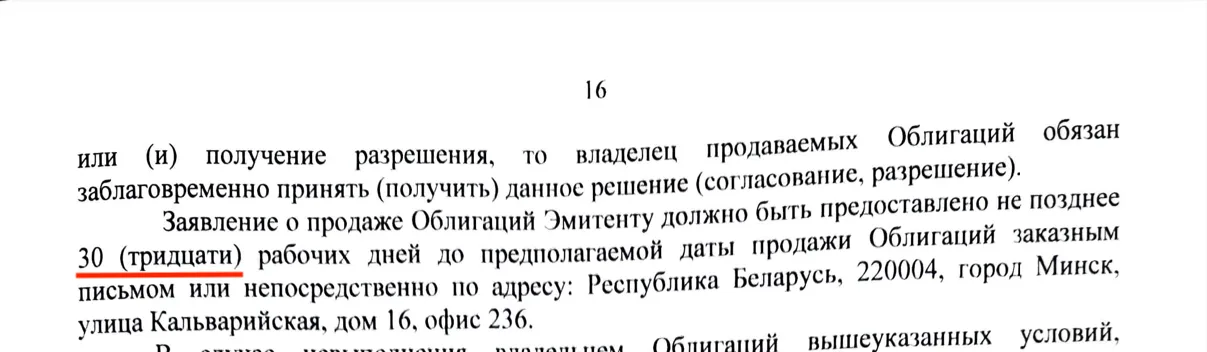
Given postal delivery times, we strongly recommend sending the request before 23 June 2021. Check the content of the request with your broker.
Translated from Russian. First published in the “Belarusian Issuers” Telegram channel. Charts and screenshots are in Russian. This is not investment advice.