Reliability analysis of the issuer AAA Solutions LLC
AAA Solutions LLC has two bond issues: in EUR (7.00%, maturing February 2024) and in USD (7.55%, maturing September 2022).
Lines of business:
- transport services (freight, satellite tracking, cargo insurance and customs clearance, forwarding) — 90% of revenue;
- information technology (cloud infrastructure, data analysis, software development, interfaces) — 10% of revenue.
Revenue for 2018 was BYN 2.4 million; for January–September 2019, BYN 2.9 million.
Operating margin is 29%, net margin 26%.
Company website (freight): aaatrans.by
Company website (IT), with the prospectus and financial statements for 2018 and January–September 2019: a-solutions.by/doc.html
OPERATING RISK ANALYSIS
Country risk
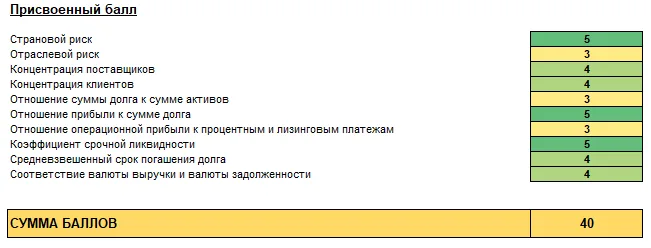
Revenue is very diversified (more than 10 countries): 38% comes from Poland, 15% from Lithuania, 11% from the Netherlands and only 4% from Belarus. The revenue-weighted country rating is 0.89 out of 1. Score 5 of 5 (very low risk).
Data source: company management
Industry risk
In a crisis, freight revenue falls by 10.7% on average and IT revenue by 5.9%. The revenue-weighted figure is −10.2%, equal to the average fall across all industries of 10.2%. Score 3 of 5 (medium risk).
Data source: prospectus, clarified by company management
Supplier concentration
The main fuel supplier (Total) accounted for 40% of supplies in 2018. At the same time fuel is no more than 20% of cost of sales, so no more than 8% of cost of sales depends directly on the main supplier. Score 4 of 5 (low risk).
Data source: prospectus, clarified by company management
Customer concentration
The largest customer accounts for 5% of revenue, so the company is almost independent of large customers. Score 4 of 5 (low risk).
Data source: company management
FINANCIAL RISK ANALYSIS
Debt to total assets
Total debt on loans and bonds is about BYN 2.2 million; total assets on the balance sheet as of 30 September 2019 (excluding leased assets) are about BYN 5.0 million. Debt to assets is therefore 43%. Score 3 of 5 (medium risk).
Data source: financial statements (total assets), company management (total debt).
Net profit to debt
Net profit for January–September 2019 was BYN 996 thousand. For this indicator we use an estimated annual net profit of BYN 1.3 million (BYN 996 thousand / 3 × 4), about 61% of total debt. In theory the company could repay about 60% of its debt from one year's profit. Score 5 of 5 (very low risk).
Data source: financial statements (net profit), company management (total debt).
Operating profit to interest and lease payments
Operating profit for January–September 2019 was BYN 1.1 million. As above, we use an estimated annual operating profit of BYN 1.5 million (BYN 1.1 million / 3 × 4) and conservatively assume it will not grow. We also assume lease payments are included in selling expenses — taking this into account, average operating profit before lease payments over the next 5 years will be BYN 1.9 million, 4.1 times the average projected annual interest and lease payments in 2019–2023 (about BYN 460 thousand). Note, however, that in 2020 the company has to pay the equivalent of BYN 1.2 million in interest and lease payments (more than half of its operating profit), so it will be vital to at least keep operating profit at or near the current level next year. Score 3 of 5 (medium risk).
Data source: financial statements (operating profit), company management (lease and interest payments).
Quick ratio
As of 30 September 2019 the company had short-term receivables of BYN 1.4 million, short-term financial investments of BYN 0, cash of BYN 7 thousand and current liabilities of BYN 288 thousand. The quick ratio is 5.0. Score 5 of 5 (very low risk).
Data source: financial statements
Weighted average debt maturity
The weighted average debt maturity is 3.5 years. Score 4 of 5 (low risk).
Data source: company management
Match between revenue currency and debt currency
90% of revenue is in EUR, 5% each in RUB and BYN. Meanwhile 60% of debt is in EUR, 15% in RUB, 10% in USD and 5% in BYN. The match is not perfect, but very high. Score 4 of 5 (low risk).
Data source: company management
SUMMARY
Total score: 40 out of 50.
Strengths from a creditworthiness perspective:
- The company is growing fast with good profitability and generates revenue that is substantial relative to its debt.
- The company is not exposed to high country risk and has no critical dependence on large customers or suppliers.
- The company should have no problems repaying current liabilities.
- Currency risk is low thanks to a good match between revenue and debt currencies.
Weaknesses from a creditworthiness perspective:
- Including leases, the debt load is fairly high, with a peak in lease payments in 2020, so the company must at least avoid a fall in operating profit to keep servicing its debt and lease payments without difficulty.
- Freight transport is an industry quite exposed to economic downturns.
DISCLAIMER
This post is not investment advice and is written for educational purposes only. Under no circumstances does it constitute a guarantee by the author of the bond issuer's reliability or that the issuer will meet its obligations on time and in full.
USEFUL LINKS
Questions for the issuer? You can ask them here: t.me/aaasolutqa
Subscribe to my channel: t.me/belarus_finance
Channel analysing Belarusian corporate bond issuers: t.me/belarus_issuers
Translated from Russian. First published in the “Belarusian Issuers” Telegram channel. Charts and screenshots are in Russian. This is not investment advice.